Building your future together.

Getting Started Is Easy, Contact Me Today!

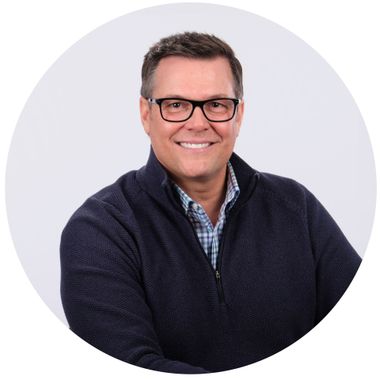
CHRISTOPHER J. COLLINS

MORTGAGE PROFESSIONAL

Thank you for visiting my website, I’m Christopher Collins, mortgage professional with XEVA mortgage. Having over 20 years of experience as a mortgage broker, I work with my clients to provide the very best solutions based on their individual needs and goals. My focus is to help build you and your families financial future together which doesn't stop at the best rate or lender.  I believe success includes long lasting relationships built on results, and trust.


I began my mortgage career in 2000 with RBC-Royal Bank, learning early on the value of people, teamwork and urgency while serving my clients needs, always looking out for the very best products and solutions for their long-term financial success. During my time at RBC, I'm proud to have had the honour of being the #1 mortgage specialist in Canada for several years, being a 4-time recipient of the "LEO Award”, which is RBC’s highest honour. My greatest achievement however has always been building many long-lasting relationships in serving my clients and the honour of their continued referrals.


As your trusted mortgage advisor, I understand that the importance of proper advice while shopping for the right mortgage for you, is critical. When looking to get pre-approved, refinance, renew or switch your existing mortgage, we will guide you through the complexities of our ever-changing mortgage landscape, providing you the very best solution with an exceptional client experience for life!


Partnering with XEVA mortgages, one of the most respected mortgage brokerages in Canada will provide our clients continued access to the very best mortgage options available. We work for you, not the banks.


RBC-Royal Bank LEO Award Winner
Working With Me Is SImple

Get started right away

The best place to start is to connect with me directly. My commitment is to listen to your needs, assess your financial situation, provide professional mortgage advice, and guide you through the mortgage process.

Get clarity

Sorting through all the different mortgage lenders, rates, terms, and features can be overwhelming. Let me cut through the noise. I'll outline the best mortgage products available with your needs in mind.

Proceed with confidence

My goal is to make sure you know exactly where you stand at all times. From your initial application through your mortgage renewal, I'm available to answer any questions for as long as you need a mortgage. I've got you covered.
Nice things people have said about working with me.

SEE WHAT YOU CAN AFFORD

Let's Run Some Numbers.
Get started by completing my online mortgage application.

APPLY NOW

I'll let you know exactly where you stand so you can proceed with confidence.

Mortgage articles to keep you informed.
By Christopher J. Collins • November 4, 2026
Missed a Credit Card or Line of Credit Payment? Here’s What to Do If you’ve missed a payment on a credit card or line of credit and you’re worried about how it might affect your credit—or your future mortgage—this is for you. First things first: 👉 If you currently have an overdue balance, log in and make the minimum payment now. Seriously. Do that first. Everything else can wait. If You’re Only a Few Days Late Here’s the good news: Credit bureaus don’t record late payments until they reach 30 days past due. So if you missed a due date by a few days and paid it as soon as you noticed, it typically won’t show up on your credit report as a late payment—as long as you’re under the 30-day mark. That said, it never hurts to double-check. You can call your credit card company, explain what happened, and confirm the account is back in good standing. If you normally pay on time, they may even reverse the interest charged. It doesn’t hurt to ask. If You’re 30, 60, or 90 Days Behind If payments have gone past 30 days, your credit has likely been impacted—but the situation is still fixable. The most important step is to: Bring all accounts current as soon as possible Make at least the minimum payment on every account The faster you catch up, the more you limit the damage. Ignoring missed payments only makes things worse. If Cash Flow Is Tight If you’re struggling to make payments, communication matters. Contact your lender and keep them informed—even if you can’t pay right away. Lenders are far more willing to work with you when you’re transparent. What hurts your credit most is silence . If lenders don’t hear from you after repeated missed payments, they may write the balance off as bad debt and send it to collections. Collections can significantly impact your credit and stay on your report for years. How This Affects Mortgage Qualification Repeated missed payments can make qualifying for a mortgage more difficult—but timing matters. Once you’re back to making regular, on-time payments: Your credit can improve over time The impact of past mistakes becomes less significant If you’re planning to buy a home in the next couple of years, addressing credit issues early gives you far more options later. Final Thoughts Missing a payment doesn’t mean you’re “bad with money,” and it doesn’t mean homeownership is off the table. What matters most is how quickly you respond and how consistent you are going forward . If you’d like help reviewing your credit report or understanding where you stand from a mortgage perspective, feel free to connect. I’d be happy to walk through it with you and help you create a clear path forward.
By Christopher J. Collins • October 28, 2026
On October 28, 2026, the Bank of Canada raised its key interest rate by 0.25%, bringing it to 2.5%. If you have a mortgage, are shopping for a home, or have a renewal coming up, this decision matters. Here is a plain-language look at what changed, why it happened, and what it could mean for you.
By Christopher J. Collins • October 21, 2026
Porting Your Mortgage: What You Need to Know Before You Rely on It Porting a mortgage means transferring your existing interest rate, remaining term, and outstanding balance from your current home to a new one when you sell and buy again. While some lenders—especially big banks—make porting sound simple, the reality is that porting a mortgage is often complex and far from guaranteed . It’s not a magic solution, and it doesn’t mean you automatically get to keep your old mortgage on your new home. In many ways, porting a mortgage feels like applying for a brand-new one—often with more conditions . Here’s why. 1. You Still Have to Re-Qualify Even though you already have the mortgage, the lender will reassess you. If you: Changed jobs Moved to a new city Are on probation Switched industries or income types …the lender may decline the port. Your previous approval does not carry over automatically. 2. The New Property Must Be Approved The lender also reassesses the new property . Just because they accepted your previous home as collateral doesn’t mean they’ll approve the next one. Expect: A new appraisal A review of the property’s condition Scrutiny around marketability and value If the lender isn’t comfortable with the property, the port can fail. 3. Property Values Rarely Line Up Perfectly Most moves involve a price difference. Buying a more expensive home: You’ll likely need additional funds at a blended rate, which can increase your payment. Buying a less expensive home: You may face a penalty for reducing the mortgage balance. Either scenario can affect your costs. 4. You Still Need a Down Payment Porting doesn’t mean you “swap houses” without cash. You still need: A down payment on the new purchase Closing costs Funds available at the right time This often surprises buyers. 5. Penalties Usually Still Apply (At First) Most lenders: Charge the full mortgage penalty when you sell Refund it only after the port is successfully completed If you’re relying on sale proceeds for your down payment, this temporary penalty can create a cash-flow issue. 6. Timelines Rarely Line Up Perfectly Real estate markets don’t cooperate. You might: Sell quickly but struggle to buy Find a home quickly but wait months to sell Closing dates rarely align, which complicates porting even further. 7. Port Periods Vary by Lender This is where the fine print matters. Depending on the lender, the port window may be: Same day only 30 days 90 days Up to 6 months If the port window is short, both transactions must close within that timeframe—or the port fails. Longer port periods offer flexibility, but also carry the risk of selling first and not finding a replacement property in time. The Bottom Line Porting your mortgage can make sense—especially if you have a strong rate and are buying a similar-priced home. But it is not guaranteed , and it comes with conditions, risks, and timing challenges. Portability is a feature, not a promise. Before you rely on it, it’s important to review all your options , including whether staying with your lender actually makes financial sense. If you’re planning to sell and buy, I’d be happy to walk you through the process, explain your options clearly, and help you decide whether porting is the right move—or if another strategy makes more sense.
By Christopher J. Collins • November 4, 2026
Missed a Credit Card or Line of Credit Payment? Here’s What to Do If you’ve missed a payment on a credit card or line of credit and you’re worried about how it might affect your credit—or your future mortgage—this is for you. First things first: 👉 If you currently have an overdue balance, log in and make the minimum payment now. Seriously. Do that first. Everything else can wait. If You’re Only a Few Days Late Here’s the good news: Credit bureaus don’t record late payments until they reach 30 days past due. So if you missed a due date by a few days and paid it as soon as you noticed, it typically won’t show up on your credit report as a late payment—as long as you’re under the 30-day mark. That said, it never hurts to double-check. You can call your credit card company, explain what happened, and confirm the account is back in good standing. If you normally pay on time, they may even reverse the interest charged. It doesn’t hurt to ask. If You’re 30, 60, or 90 Days Behind If payments have gone past 30 days, your credit has likely been impacted—but the situation is still fixable. The most important step is to: Bring all accounts current as soon as possible Make at least the minimum payment on every account The faster you catch up, the more you limit the damage. Ignoring missed payments only makes things worse. If Cash Flow Is Tight If you’re struggling to make payments, communication matters. Contact your lender and keep them informed—even if you can’t pay right away. Lenders are far more willing to work with you when you’re transparent. What hurts your credit most is silence . If lenders don’t hear from you after repeated missed payments, they may write the balance off as bad debt and send it to collections. Collections can significantly impact your credit and stay on your report for years. How This Affects Mortgage Qualification Repeated missed payments can make qualifying for a mortgage more difficult—but timing matters. Once you’re back to making regular, on-time payments: Your credit can improve over time The impact of past mistakes becomes less significant If you’re planning to buy a home in the next couple of years, addressing credit issues early gives you far more options later. Final Thoughts Missing a payment doesn’t mean you’re “bad with money,” and it doesn’t mean homeownership is off the table. What matters most is how quickly you respond and how consistent you are going forward . If you’d like help reviewing your credit report or understanding where you stand from a mortgage perspective, feel free to connect. I’d be happy to walk through it with you and help you create a clear path forward.
By Christopher J. Collins • October 28, 2026
On October 28, 2026, the Bank of Canada raised its key interest rate by 0.25%, bringing it to 2.5%. If you have a mortgage, are shopping for a home, or have a renewal coming up, this decision matters. Here is a plain-language look at what changed, why it happened, and what it could mean for you.
By Christopher J. Collins • October 21, 2026
Porting Your Mortgage: What You Need to Know Before You Rely on It Porting a mortgage means transferring your existing interest rate, remaining term, and outstanding balance from your current home to a new one when you sell and buy again. While some lenders—especially big banks—make porting sound simple, the reality is that porting a mortgage is often complex and far from guaranteed . It’s not a magic solution, and it doesn’t mean you automatically get to keep your old mortgage on your new home. In many ways, porting a mortgage feels like applying for a brand-new one—often with more conditions . Here’s why. 1. You Still Have to Re-Qualify Even though you already have the mortgage, the lender will reassess you. If you: Changed jobs Moved to a new city Are on probation Switched industries or income types …the lender may decline the port. Your previous approval does not carry over automatically. 2. The New Property Must Be Approved The lender also reassesses the new property . Just because they accepted your previous home as collateral doesn’t mean they’ll approve the next one. Expect: A new appraisal A review of the property’s condition Scrutiny around marketability and value If the lender isn’t comfortable with the property, the port can fail. 3. Property Values Rarely Line Up Perfectly Most moves involve a price difference. Buying a more expensive home: You’ll likely need additional funds at a blended rate, which can increase your payment. Buying a less expensive home: You may face a penalty for reducing the mortgage balance. Either scenario can affect your costs. 4. You Still Need a Down Payment Porting doesn’t mean you “swap houses” without cash. You still need: A down payment on the new purchase Closing costs Funds available at the right time This often surprises buyers. 5. Penalties Usually Still Apply (At First) Most lenders: Charge the full mortgage penalty when you sell Refund it only after the port is successfully completed If you’re relying on sale proceeds for your down payment, this temporary penalty can create a cash-flow issue. 6. Timelines Rarely Line Up Perfectly Real estate markets don’t cooperate. You might: Sell quickly but struggle to buy Find a home quickly but wait months to sell Closing dates rarely align, which complicates porting even further. 7. Port Periods Vary by Lender This is where the fine print matters. Depending on the lender, the port window may be: Same day only 30 days 90 days Up to 6 months If the port window is short, both transactions must close within that timeframe—or the port fails. Longer port periods offer flexibility, but also carry the risk of selling first and not finding a replacement property in time. The Bottom Line Porting your mortgage can make sense—especially if you have a strong rate and are buying a similar-priced home. But it is not guaranteed , and it comes with conditions, risks, and timing challenges. Portability is a feature, not a promise. Before you rely on it, it’s important to review all your options , including whether staying with your lender actually makes financial sense. If you’re planning to sell and buy, I’d be happy to walk you through the process, explain your options clearly, and help you decide whether porting is the right move—or if another strategy makes more sense.
Show More